
What a Denver Auto Injury Claim Involves: Evidence, Coverage, and the Colorado Deadline
Key Points(5)
- A Denver crash creates two separate problems at once.
- The first is medical: getting evaluated, following treatment, and understanding what has actually been injured.
- The second is evidentiary: preserving a record of what happened before it disappears.
- The two overlap, because medical records are usually the most durable evidence of an injury, but they are not the same task and they run on different clocks.
- This article is general information for Colorado drivers, not legal or medical advice.
A Denver crash creates two separate problems at once. The first is medical: getting evaluated, following treatment, and understanding what has actually been injured. The second is evidentiary: preserving a record of what happened before it disappears. The two overlap, because medical records are usually the most durable evidence of an injury, but they are not the same task and they run on different clocks.
This article is general information for Colorado drivers, not legal or medical advice. Every collision turns on its own facts, and the right response depends on the injuries, the available insurance, and the evidence that survives the first few weeks.
The First Week Decides What Evidence Still Exists
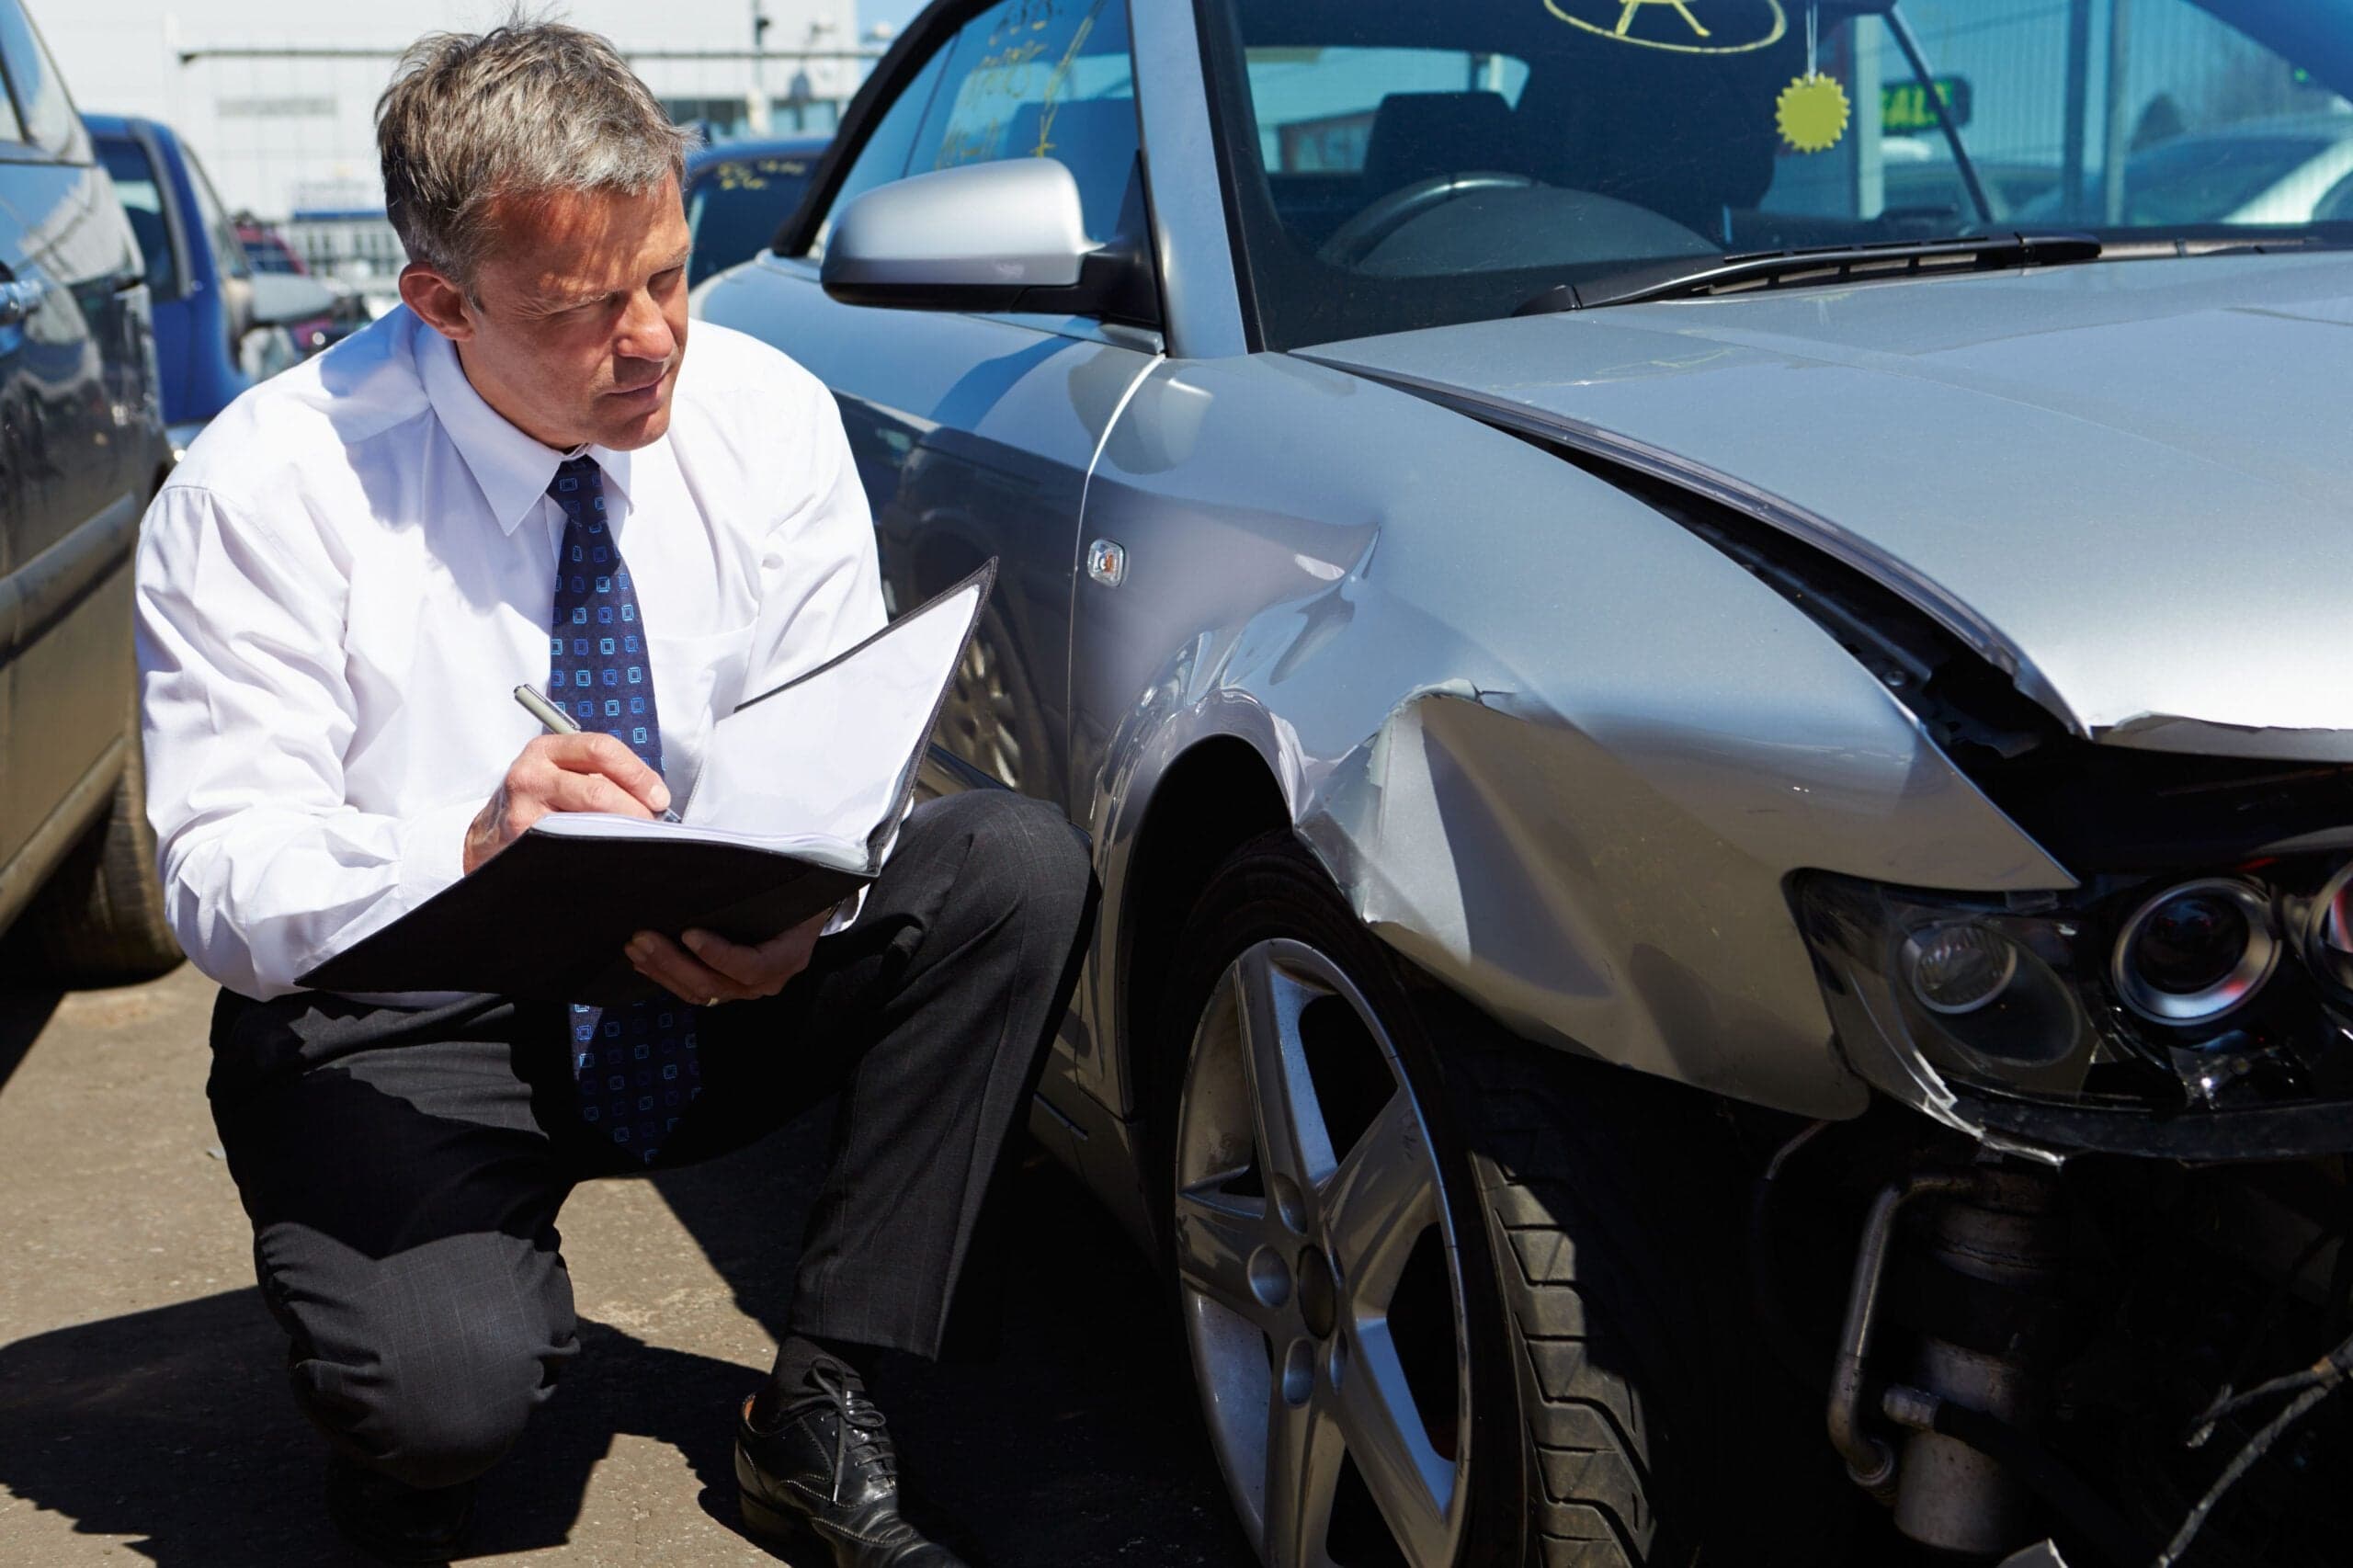
Crash evidence degrades quickly and unevenly. Vehicles get repaired or sold for salvage. Businesses overwrite security footage on a rolling cycle, often within one to four weeks. Witnesses move, change numbers, and lose the details that made their account useful. Road conditions change with the weather. None of that is dramatic, and none of it announces itself — it simply means the record available in month three is thinner than the record available in week one.
The practical response is to capture what is capturable and to ask, in writing, that anyone holding a recording preserve it. That includes nearby businesses, apartment buildings, parking structures, and any rideshare or delivery platform involved. A short written preservation request costs nothing and creates a dated record that the request was made.
What Is Worth Preserving
● Photographs and video of the vehicles, roadway, signals, lane markings, debris, weather, and visible injuries — originals, not screenshots or social media re-uploads.
● The crash report number, responding agency, and officer information.
● Names and direct contact details for independent witnesses.
● Dashcam footage, saved before the device overwrites it.
● Repair estimates, towing invoices, storage notices, and photographs taken before any repair work begins.
● Medical records, imaging results, prescriptions, referrals, work restrictions, and a dated symptom log.
● Pay records, employer correspondence, and documentation of missed shifts or modified duties.
Why a Denver Auto Injury Claim Often Involves More Than One Policy
Drivers tend to assume that an injury claim runs against the at-fault driver's liability policy and stops there. In practice, several sources of coverage may be in play at once, and which ones apply depends on facts that are not always obvious at the scene.
● The at-fault driver's bodily injury liability coverage, subject to its limits.
● Your own uninsured or underinsured motorist coverage, which becomes central when the at-fault driver has no insurance or carries limits below the value of the loss.
● Medical payments coverage, which can pay treatment costs while fault remains disputed.
● An employer's commercial policy, when the other driver was working at the time.
● Rideshare or delivery platform coverage, which turns on the driver's app status at the moment of impact.
● Health insurance, which may pay treatment and then assert a lien or subrogation interest against any recovery.
A Denver auto injury claim can therefore require reading several policies rather than one, and the order in which they are approached affects what gets paid and what has to be repaid later. Identifying every available policy early is usually more valuable than arguing about the first settlement figure.
How Colorado Evaluates Fault
Colorado uses modified comparative negligence. An injured person's recovery is reduced by their share of responsibility, and if that share is equal to or greater than the responsibility of the party they are pursuing, recovery is barred. That rule makes early, casual statements about fault more consequential than they appear at the roadside.
Fault is generally reconstructed from several sources rather than a single one: the crash report, witness accounts, vehicle damage patterns, scene photographs, traffic or security video, dashcam footage, roadway design, and sometimes electronic data from the vehicles. A police report is important evidence, but it does not conclusively resolve fault, and insurers routinely reach a different conclusion than the responding officer.
The Deadlines Worth Confirming Early
Most Colorado civil claims for bodily injury or property damage arising from the use or operation of a motor vehicle are subject to a three-year limitation period under C.R.S. § 13-80-101. That is the headline rule, and it is not the only one. Claims involving a public entity generally require written notice within 182 days under the Colorado Governmental Immunity Act. Insurance policies impose their own, much shorter, notice obligations. A claim on behalf of a minor may follow a different timeline entirely.
Confirm the applicable deadline against the specific facts rather than a general summary found online, and treat the insurance notice requirement as separate from the litigation deadline. Meeting one does not satisfy the other.
What Makes Professional Review Worth the Call
Not every collision needs a lawyer. A property-damage-only crash with no injury, no disputed liability, and no coverage question is usually handled directly with the insurer. Review tends to be worth the time when one or more of the following is true:
● The injuries required emergency care, imaging, surgery, or ongoing treatment.
● Fault is disputed, or more than one driver may share responsibility.
● A commercial vehicle, rideshare driver, delivery driver, or government vehicle was involved.
● The at-fault driver was uninsured or carried minimum limits.
● The insurer is pressing for a recorded statement or a broad medical authorization early.
● A settlement has been offered before the medical outlook is clear.
● Someone died, or an injury appears likely to be permanent.
Questions Worth Asking in a First Consultation
● Which insurance policies may apply to this crash, and in what order?
● What evidence should be preserved right now, and who should request it?
● How could a shared-fault argument affect this claim?
● Which deadlines apply, and are any of them shorter than three years?
● How will medical bills, health insurance liens, and any medical payments coverage be handled?
● What does the fee agreement cover, and how are case costs treated if there is no recovery?
A Practical Order of Operations
● Get medical evaluation and follow the treatment plan.
● Report the crash as your policy requires, and record the claim number.
● Preserve photographs, video, witness details, and the crash report number.
● Send written preservation requests to anyone holding relevant footage.
● Keep every bill, receipt, and item of insurer correspondence in one file.
● Track symptoms, missed work, and daily limitations as they happen, not from memory.
● Confirm the applicable deadlines before they become urgent.
● Get the claim reviewed before giving a detailed recorded statement or signing a release.
Final Thoughts
The strongest injury claims are rarely the ones argued most forcefully. They are the ones documented most carefully — where the treatment history is consistent, the evidence was preserved while it still existed, and every applicable policy was identified before anyone started negotiating. None of that requires a decision on day one. It requires keeping the options open long enough to make an informed one.

